

By Justin James McShane
$183 Billion and 93 Rigs: The Physics Behind the Biggest Oil Deal Headline
Executive Orientation
As of the evening of August 28, 2026, President Trump announced that the United States has entered an agreement with Venezuela’s interim government securing “majority U.S. control” of more than 65 billion barrels of proven Venezuelan oil reserves “at no cost to the American taxpayer,” via a partnership with private business. He described it as “THE BIGGEST OIL DEAL IN WORLD HISTORY,” stating it more than doubles U.S. oil reserves and will increase supply and lower gasoline prices. Negotiators named were Secretary of State Marco Rubio, Secretary of War Pete Hegseth, and Venezuelan Interim President Delcy Rodríguez. Secretary Rubio separately described it as bringing nearly $100 billion in private investment.
TL;DR
President Trump announced on 28 August 2026 “majority U.S. control” of more than 65 billion barrels of Venezuelan proved reserves “at no cost to the taxpayer,” via private partners, Rubio, Hegseth, and interim President Delcy Rodríguez. The executed field list, lease or JV text, and entitlement language have not been published.
Pre-announcement sourcing described 17 fields (Orinoco greenfields plus mature Maracaibo) and about 90 billion barrels. The 65 billion figure is a negotiated slice of that package, not new oil in the ground.
Reservoirs stay vested in the Venezuelan state under the 29 January 2026 hydrocarbons reform. Private operators can run fields at their own risk, sell crude, pay royalty up to 30 percent and tax up to 15 percent, and use international arbitration. A 100-year U.S. title claim sits on contested constitutional ground.
U.S. proved crude plus condensate was 46.0 billion barrels at year-end 2024. The SPR is near 290 million barrels. Those numbers explain the politics. They do not move a workover rig.
Hold-flat capex at ~1.1–1.25 million b/d is about $53 billion over 15 years. Fast workovers can add 200–350 kb/d in 2–3 years for about $14 billion. A path to 2 million b/d by ~2032 and 3 million by 2040 is about $183 billion, including $65 billion-plus of midstream and upgrader repair. The $100 billion private-investment headline is the first-decade check, not the full bill.
Binding constraints are idle wells, two active onshore rigs versus a 93-rig 2028 target, ruined upgraders, diluent, grid power, and a drained technical workforce. Geology is not the constraint.
Independents (Hunt Oil, Pacific Coast, SLB services) are already signing and can put workover iron to work in weeks to 18 months. Majors other than Chevron need 18–36 months to FID and the early 2030s for material new Orinoco volumes. Chevron is targeting ~375 kb/d by end-2028 from existing cash flow.
Merey (~16° API, 2.5–3.4% sulfur) and Boscan (~10° API, ~5.4% sulfur) fit U.S. Gulf Coast cokers that shale light-sweet does not fill. Venezuela is already the No. 2 U.S. crude import source at ~662 kb/d versus Canada at ~3.53 million b/d.
Incremental Venezuelan heavy can displace waterborne Maya, residual Mid-East sour, and some WCS at the Gulf Coast over 4–8 years if the spend shows up. It does not retire pipeline Canada or Ras Tanura. Treat 65 billion barrels as undeveloped inventory under contested title until the annexes are public.
Introduction
The 65-billion-barrel headline is a political instrument. The production system is a corroded industrial plant that still needs iron, diluent, power, and people.
On the evening of 28 August 2026, President Trump announced that the United States had entered an agreement with Venezuela’s interim government securing “majority U.S. control” of more than 65 billion barrels of proven reserves “at no cost to the American taxpayer,” through a partnership with private business. He called it the biggest oil deal in world history and said it more than doubles American oil reserves. Secretary of State Marco Rubio and Secretary of War Pete Hegseth were named as the U.S. principals. Interim President Delcy Rodríguez was named on the Venezuelan side. Rubio separately framed the package as unlocking nearly $100 billion in private investment. The executed annexes, field list, entitlement language, and offtake contracts have not been published in the hours since the post. That gap is the first fact that matters.
What the market is being asked to price is not a title deed to 65 billion barrels. It is a political claim of control over a subset of Venezuela’s 303-billion-barrel proved reserve base, layered onto a post-Maduro sales regime that already routes cargoes through U.S.-supervised accounts, and onto a January 2026 hydrocarbons-law reform that still leaves the reservoirs vested in the Venezuelan state.
What Was Actually Negotiated
In the 48 hours before the announcement, three independent reporting lines described the same transaction. Reuters reported a U.S. effort to lock in a group of Venezuelan fields for development by American companies, with resulting supply guaranteed to the United States. A source said a “lease” was under consideration as the legal wrapper, followed by an auction or tender of individual fields to U.S. producers. Reuters said it had seen a list of 17 fields mixing undeveloped Orinoco Belt greenfields with mature Lake Maracaibo acreage, some of it previously operated by a small Chinese firm under a Maduro-era contract. Axios described more than a dozen productive fields carrying about 90 billion barrels of proved reserves—roughly one-third of the national total—and an ownership stake in return for private development that would send more revenue back to Caracas. The Washington Post described long-term contracts on that same order of magnitude and noted that several of the 17 fields lack export infrastructure. Bloomberg sourcing mentioned a possible 100-year lease construct. The announced 65-billion-barrel figure is therefore a negotiated slice or a re-characterized “majority control” claim on that package, not a newly discovered resource. Field names remain unpublished.
U.S. proved crude plus lease condensate stood at 46.0 billion barrels at year-end 2024. Adding 65 billion barrels on paper would more than double that stock. The Strategic Petroleum Reserve sat near 290 million barrels in late August 2026, a multi-decade low after the 2022 Ukraine drawdown and the February 2026 Iran/Hormuz releases. Those two numbers explain the politics. They do not move a single workover rig.
Two Legal Systems, One Reservoir Title Problem
Venezuelan Constitution Article 302 still reserves hydrocarbons to the state. The Organic Hydrocarbons Law was partially reformed and published on 29 January 2026 in Special Official Gazette 6.978. The reform ends the Chávez-era requirement that PDVSA hold a controlling stake in mixed companies. Private firms, domestic or foreign and domiciled in Venezuela, may now conduct primary activities—exploration, extraction, collection, transportation, and storage—at their own cost, account, and risk under production contracts or amended mixed-company rules. Operators may commercialize crude and derivatives directly and control cash flow. Reservoirs remain vested in the state. Royalty is capped at 30 percent of extracted hydrocarbons not used in operations and may be paid in cash or kind. The Ministry of Hydrocarbons may set a lower rate to preserve “economic equilibrium.” An integrated hydrocarbons tax is capped at 15 percent of monthly gross income. Disputes may go to Venezuelan courts or to mediation and arbitration, including international seats. Mixed-company terms historically ran 25 years plus one 15-year extension. The statute does not create a 100-year acreage lease. Any long-duration “U.S. control” construct therefore sits on contested constitutional ground and can be challenged or reversed by a later assembly.
On the U.S. side, the architecture is already live. Since the January 2026 capture of Nicolás Maduro, Washington has directed Venezuelan oil marketing. Proceeds settle first in U.S.-controlled accounts and are disbursed at U.S. discretion. OFAC’s 27 August 2026 package includes General License 52B, which authorizes established U.S. entities—organized on or before 29 January 2025—to transact with PDVSA and entities in which PDVSA owns 50 percent or more, provided dispute resolution sits in the United States, the United Kingdom, France, or Singapore, and monetary payments to blocked persons, other than local taxes and fees, go into Treasury-designated Foreign Government Deposit Funds. Companion licenses cover Venezuelan-origin oil and petrochemicals, U.S.-origin diluent sales, oilfield goods and services, and operations by named companies including Chevron, Shell, BP, Eni, Repsol, and Maurel & Prom. Gold, crypto, debt swaps, blocked vessels, and dealings with Russia-, Iran-, DPRK-, Cuba-, or China-linked entities remain prohibited. That is the compliance box any independent or major must fit inside.
“Majority U.S. control” in the announcement is therefore best read as a bundle of operatorship, working interest, offtake preference, and U.S.-supervised cash waterfalls—not fee-simple title to the rock. Reserve booking under SEC rules will turn on entitlement language that has not been released.
The Capex Schedule the Headline Omits
Venezuela is producing about 1.25 million barrels per day against a historical peak above 3 million. The Orinoco Belt holds the large majority of the 303 billion barrels and is extra-heavy crude, typically 8 to 10 degrees API in situ, high viscosity, high sulfur, high vanadium and nickel. It does not move or sell as a finished barrel without diluent or upgrading. Lake Maracaibo is mature, high water-cut, environmentally damaged, and infrastructure-starved. Geology is not the constraint. Steel, power, diluent, upgraders, and people are.
Rystad Energy’s project-level sequencing remains the broker benchmark. Holding output flat near 1.1 to 1.25 million barrels per day for fifteen years requires about $53 billion of upstream and infrastructure spend. That is maintenance. The fastest barrels are workovers. Rystad estimates 200,000 to 350,000 barrels per day can be restored in 24 to 36 months for roughly $14 billion, taking the system toward 1.4 million barrels per day. Growth beyond that requires an additional $8 to $9 billion per year from 2026 through 2040. A path to 2 million barrels per day by about 2032 and 3 million by 2040 costs about $183 billion cumulative, split approximately $102 billion upstream and $81 billion for pipelines, upgraders, terminals, and power. Infrastructure repair alone is a $65 billion-plus prerequisite. Associated service purchases run about $156 billion. At least $30 to $35 billion of international capital is required in the first two to three years to make the 2040 case plausible. Francisco Monaldi at Rice University’s Baker Institute has put the decade-scale rebuild near $100 billion. Some industry estimates run as high as $220 billion once corrosion, theft, and upgrader rebuilds are fully priced. The administration’s public target of $100 billion in private investment sits inside that band if it is treated as the first-decade international check rather than the full life-cycle bill.
The first dollars go to well intervention, not to new Orinoco pads. Thousands of wells are idle. Pulling units and light workover rigs move first. SLB has said smaller workover units deploy before drilling rigs and that it can reactivate as many as 15 of its own stacked rigs inside Venezuela within a year, with up to four possibly back before year-end 2026 if contracts are signed. Baker Hughes counted about two active onshore drilling rigs in July 2026. The ministry has identified a requirement for 93 active drilling rigs by 2028. That gap is iron and crews, not reserves.
Upgraders are the second bottleneck. Petropiar and the other Jose-complex trains were built to turn 8-degree bitumen into a 16- to 26-degree synthetic or blendstock. Several have been run into the ground. Rebuilding a train is a multi-year industrial project. Diluent is the third bottleneck. U.S. naphtha and light crude must flow south in volume if extra-heavy output rises faster than upgrader capacity. The January 2026 Department of Energy fact sheet already contemplated that flow. Power is the fourth. Grid failures take wells offline. People are the fifth. PDVSA and the service sector lost a generation of petroleum engineers, completion technicians, welders, and supervisors. Only a minority of the diaspora will return without durable pay, security, and schools. Firms are already naming Venezuelan country managers and posting for technicians. That is a multi-year rebuild, not a press-cycle event.
Orinoco greenfield breakevens have been cited in the mid-$60s to $80-plus per barrel Brent depending on royalty take and whether an upgrader is required. Mature conventional workovers in the east and west can be cash-generative at much lower prices. That is why the first commercial activity is not a Carabobo mega-project.
Two Clocks: Independents and Majors
The clocks are already different on the ground.
Independents and service companies are inside the fence. Hunt Oil signed a hydrocarbon production-participation contract in Houston on 18 August 2026 covering the Caro and Carisito fields in the east—light and medium crude plus gas, which is exactly the molecule you want as diluent and blendstock. Crossover Energy was alongside. SLB signed a nationwide reservoir-studies and services framework the same week. Pacific Coast Energy, a small California producer with European backing, is finalizing field packages and is moving faster than ExxonMobil or ConocoPhillips. The Department of Energy has hosted wildcatters from the Continental and Hilcorp lineages. The new production-contract model is built for this cohort: operator at own cost and risk, state keeps reservoir title, flexible royalty at or below 30 percent, arbitration available, smaller checks, faster payout. Contract to first workover rig can be weeks to a few months because equipment is already in country or in Houston and the Caribbean. Meaningful incremental production from a given mature block is a 6-to-18-month problem. Scaling a portfolio of mature assets to tens of thousands of barrels per day is an 18-to-36-month problem. Independents will not open greenfield Orinoco. They will pick over shut-in conventional wells and sell services.
Majors are on a different calendar. Chevron never left. Current joint-venture output is about 260,000 barrels per day, almost entirely heavy crude moving to the U.S. Gulf Coast. Chevron is targeting as much as 375,000 barrels per day by the end of 2028, funded from existing Venezuelan cash flow, and has already raised its Petroindependencia working interest to 49 percent and added Ayacucho 8. Shell, Eni, Repsol, and BP have positions or 2026 agreements. ExxonMobil and ConocoPhillips remain the slowest counterparties because expropriation memory, outstanding claims, and Orinoco fiscal terms have not been closed. License and joint-venture migration can complete through the first half of 2027. Front-end engineering, security planning, offtake, diluent contracts, and reserve-booking legal opinions take 12 to 24 months. First major final investment decision on a new or expanded Orinoco or upgrader package sits in 2027 to 2029. First oil from a new pad or a refurbished upgrader train is three to five years after FID. Material new extra-heavy volumes, as distinct from workover barrels, arrive in the early 2030s. Majors will book reserves only if working interest, operatorship, and entitlement survive SEC and IFRS tests. That is a legal product. It is not a Truth Social post.
Why the Molecule Matters
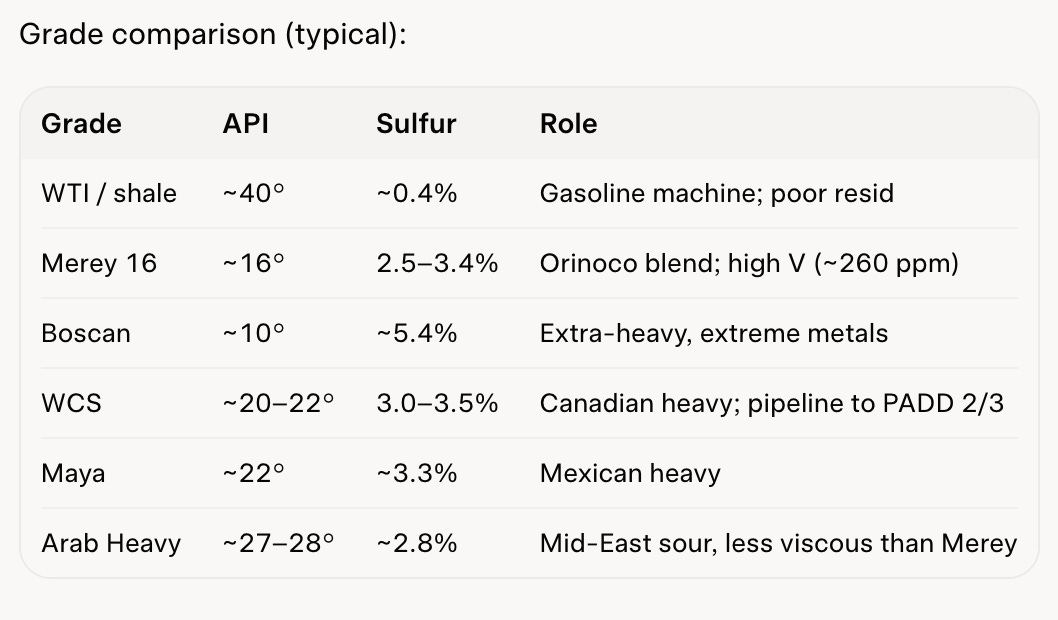
U.S. shale is light and sweet. WTI sits near 40 degrees API and 0.4 percent sulfur. It is a gasoline and naphtha machine with a thin vacuum resid. Gulf Coast coking refineries—Valero, PBF, Marathon, Phillips 66, Chevron, ExxonMobil, Motiva—were configured over decades for Venezuelan Merey and Boscan, Mexican Maya, and Canadian Western Canadian Select. Running a light-sweet slate through a coker-heavy plant destroys coker utilization and residual-conversion economics.
Merey 16 typically tests near 16 degrees API and 2.5 to 3.4 percent sulfur, with vanadium around 260 parts per million. Boscan tests near 10 degrees API and 5.4 percent sulfur with extreme metals. WCS sits near 20 to 22 degrees API and 3.0 to 3.5 percent sulfur. Maya sits near 22 degrees API and 3.3 percent sulfur. Arab Heavy sits near 27 to 28 degrees API and 2.8 percent sulfur. Merey and Boscan are heavier and often dirtier than WCS. They are the molecules a delayed coker wants if the discount is wide enough and metals and total acid number can be managed. That is why Venezuelan crude has been the second-largest U.S. crude import source for 18 consecutive weeks. For the week ending 21 August 2026, EIA preliminary data showed Canada at 3.526 million barrels per day and Venezuela at 662,000. May 2026 Venezuelan cargoes averaged about 14.4 degrees API and 3.31 percent sulfur. The Gulf Coast is already pulling the barrel because it fits the kit.
This complementarity is real. The displacement story that follows from it is usually oversold.
Canada is not a spot cargo. It is a pipeline system. Enbridge Mainline and Keystone deliver heavy crude into PADD 2 and PADD 3 at a structurally different landed cost than a VLCC of Merey into St. James or Houston. Midcontinent cokers cannot be re-fed from Jose by water. Canadian synthetic and upgraded barrels are also a different cut than raw Merey. Iraq’s U.S. deliveries have been near zero during the Hormuz disruption. Saudi volumes into the United States are a fraction of Canada’s. Incremental Venezuelan heavy will compete first at the U.S. Gulf Coast with waterborne Maya, residual Middle East heavy, and the WCS barrels that would otherwise move south. That competition is already visible in WCS differentials when Merey is plentiful.
A path to 1.5 to 2.0 million barrels per day of exportable Venezuelan heavy by the early 2030s can substitute a large share of the incremental Gulf Coast heavy-sour slate. It does not retire 3.5 million barrels per day of Canadian pipeline crude. It does not retire Ras Tanura. A restored Venezuelan system will sell to India, China, and Europe when discounts are wide. U.S. shale still needs some heavy resid to keep cokers full. The correct framing is that Venezuela becomes the swing Western Hemisphere heavy-sour supplier to PADD 3, compresses WCS and Maya differentials, and gives U.S. complex refiners an alternative to Hormuz-exposed barrels. Time to material Gulf Coast substitution is four to eight years if the $8 to $9 billion annual spend actually appears and diluent and upgraders are solved. Time to eliminate Canadian or Middle East barrels is not on any published production path through 2040.
What the Deal Actually Buys
The January 2026 operation removed Maduro. The subsequent sales regime put Venezuelan cargoes and cash under U.S. supervision. The hydrocarbons-law reform reopened operatorship to private capital. OFAC licenses rebuilt a legal path for established U.S. entities. Chevron expanded. Hunt and SLB signed. The 28 August announcement adds a political claim of majority control over a 65-billion-barrel proved-reserve slice and an investment narrative sized to midterm gasoline politics and a depleted Strategic Petroleum Reserve.
Energy is leverage. This package attempts to convert a security event into a long-duration heavy-sour option in the Western Hemisphere while Hormuz remains a war risk and Canadian heavy remains the cheapest delivered barrel into the Midwest. The option is real. The reserve number is a headline. The production function is workovers in 2026 and 2027, midstream and people through the rest of the decade, and Orinoco steel in the 2030s.
Treat the 65 billion barrels as an undeveloped inventory under contested title until the annexes are public. Track the royalty and tax take field by field. Track rig counts, diluent imports, upgrader utilization, and Chevron’s 8-K language on reserve booking. Those four series will tell you whether this is a deal or a communiqué. Physics does not negotiate.
Conclusion
Washington bought an option, not a producing field. The announcement prices midterm gasoline politics and a hollowed-out Strategic Petroleum Reserve. The asset prices workover iron, diluent molecules, Jose upgrader steel, and a technical workforce that left the country. Until the annexes name the 17 fields, the royalty take, and who can book the barrels, treat 65 billion as undeveloped inventory under contested title.
Watch four series, not the communiqué. Rig count against the 93-unit 2028 target. Diluent flowing south. Upgrader utilization at Jose. Chevron’s reserve-booking language in the next 8-K. Those four will tell you whether this is a Western Hemisphere heavy-sour swing supply or a press cycle. Physics does not negotiate.
Sources:
1. Associated Press. (2026, August 28). Trump says U.S. has entered deal with Venezuela to control 65 billion barrels of its oil reserves. PBS NewsHour. https://www.pbs.org/newshour/politics/trump-says-u-s-has-entered-deal-with-venezuela-to-control-65-billion-barrels-of-its-oil-reserves
2. Caputo, M. (2026, August 27). Scoop: U.S. close to striking “massive” deal for Venezuelan oil fields. Axios. https://www.axios.com/2026/08/27/trump-venezuela-oil-deal-talks
3. Parraga, M., & Renshaw, J. (2026, August 27). US nears deal to secure long-term access to Venezuela’s oil reserves, sources say. Reuters. https://www.reuters.com/business/energy/us-nears-deal-secure-long-term-access-venezuelas-oil-reserves-sources-say-2026-08-27/
4. Reuters. (2026, August 28). Trump announces sweeping US grab for control of Venezuela’s vast oil reserves. https://www.reuters.com/business/energy/us-enters-into-oil-agreement-with-venezuela-trump-says-2026-08-28/
5. The Washington Post. (2026, August 28). Trump secures vast, potentially costly U.S. stake in Venezuelan oil industry. https://www.washingtonpost.com/business/2026/08/28/trump-seeks-vast-potentially-costly-us-stake-venezuelan-oil-industry/
6. CNN. (2026, August 28). Trump says US reaches deal with Venezuela to control 65 billion barrels of country’s oil reserves. https://www.cnn.com/2026/08/28/politics/trump-venezuela-oil-deal
7. Whisnant, G. (2026, August 28). Trump announces Venezuelan oil deal, says it will ‘substantially lower’ US gas prices. Newsweek. https://www.newsweek.com/trump-announces-deal-majority-us-control-venezuelan-oil-reserves-12382897
8. The Guardian. (2026, August 28). Trump announces new US oil agreement with Venezuela. https://www.theguardian.com/us-news/2026/aug/28/trump-venezuela-oil-agreement
9. U.S. Energy Information Administration. (2026, April 7). U.S. crude oil and natural gas proved reserves, year-end 2024. https://www.eia.gov/naturalgas/crudeoilreserves/
10. U.S. Energy Information Administration. (2026, August 26). Weekly preliminary crude imports by top 10 countries of origin. https://www.eia.gov/dnav/pet/pet_move_wimpc_s1_w.htm
11. U.S. Energy Information Administration. (2026, August 26). Weekly Petroleum Status Report (week ending August 21, 2026). https://www.eia.gov/petroleum/supply/weekly/
12. U.S. Department of Energy. (2026, January 7). Fact sheet: President Trump is restoring prosperity, safety and security for the United States and Venezuela. https://www.energy.gov/articles/fact-sheet-president-trump-restoring-prosperity-safety-and-security-united-states-and
13. Office of Foreign Assets Control. (2026, August 27). General License No. 52B: Authorizing certain transactions involving Petróleos de Venezuela, S.A. U.S. Department of the Treasury. https://ofac.treasury.gov/media/936831/download?inline
14. Office of Foreign Assets Control. (2026, August 27). Issuance of amended Venezuela-related general licenses and associated frequently asked questions. U.S. Department of the Treasury. https://ofac.treasury.gov/recent-actions/20260827
15. Baker McKenzie. (2026, March). Venezuela’s hydrocarbons law reform: What businesses need to know. https://www.bakermckenzie.com/en/insight/publications/2026/03/reform-organic-hydrocarbons-law-venezuela
16. Cleary Gottlieb. (2026, July 14). Venezuela’s oil reform efforts: New opportunities, unanswered questions – U.S. investor perspective. https://www.clearygottlieb.com/news-and-insights/publication-listing/venezuelas-oil-reform-efforts
17. Rystad Energy. (2026, January 6). What would it take to bring Venezuela’s oil output back to 3 million bpd? (special market update, as reported). American Journal of Transportation. https://www.ajot.com/news/what-would-it-take-to-bring-venezuelas-oil-output-back-to-3-million-bpd-rystad-energy-special-market-update
18. World Oil. (2026, January 6). Long road back for Venezuela oil as infrastructure caps growth: Rystad. https://worldoil.com/news/2026/1/6/long-road-back-for-venezuela-oil-as-infrastructure-caps-growth-rystad/
19. Rystad Energy. (2026, July 13). Venezuela’s upstream revival: Turning policy momentum into production growth. https://www.rystadenergy.com/insights/venezuelas-upstream-revival-turning-policy-momentum-into-production-growth
20. Chevron Corporation. (2026, April 13). Chevron consolidates Venezuela heavy oil position in asset swap. https://www.chevron.com/newsroom/2026/q2/chevron-consolidates-venezuela-heavy-oil-position-in-asset-swap
21. Parraga, M. (2026, August 28). Chevron to complete deal in Venezuela to migrate, expand oil projects, sources say. Reuters. https://www.reuters.com/business/energy/chevron-complete-deal-venezuela-migrate-expand-oil-projects-sources-say-2026-08-28/
22. Houston Public Media. (2026, August 19). Texas-based oil companies among first to sign contracts with Venezuela. https://www.houstonpublicmedia.org/articles/news/energy-environment/2026/08/19/559888/texas-oil-companies-venezuela-contracts/
23. Rio Times. (2026, August 27). Venezuelan crude oil now second-largest US source. https://www.riotimesonline.com/venezuela-second-us-crude-supplier-18-weeks-2026/
You do not send the Secretary of War to negotiate 100-year commercial energy concessions unless kinetic force is the unspoken baseline.
Pete Hegseth’s 65-billion-barrel Venezuelan ultimatum wasn’t executed from a position of leverage—it is an emergency attempt to cover an unmitigated physical supply failure in the Persian Gulf before diesel crack spreads blow out completely.
Read the full breakdown:
https://triggledger.substack.com/p/the-caracas-ultimatum-why-65-billion?utm_source=share&utm_medium=android&r=8gc1qf
United States should consider forming a sovereign wealth fund similar to Singapore's Temasek. The sovereign wealth fund can project finance the development of Venezuelan's oil infrastructure. Equity in these projects will pay future dividend that can be remitted to U.S treasury, improving U.S' fiscal position.
In fact, United States should use the same sovereign wealth fund to seed start ups. If even just two or three of those start ups grow into giants like Microsoft, Google, TSMC or NVDIA, the dividend income from the equity can help to improve the country's fiscal position. I don't understand why America's economic statecraft is so disorganized and uncoordinated.